In today’s market, many sellers are starting to think about lowering the sales price on their homes, especially if it’s been sitting on the market for awhile. Another option is to offer the buyer a rate buydown.
Buyers love to get a deal on a home. In some cases, having the seller contribute towards closing costs by offering to pay points or a temporary buydown, it may help get a home sold. In September Redfin says there were 63% more sellers than buyers in the market. With mortgage rates increasing, it’s harder on budgets and may affect the ability to buy a home.
One of the most common negotiation points? It’s price. But some sellers are leaving the price alone and offering to pay money towards the buyers interest rate.
A buydown is money paid at closing to lower the buyer’s mortgage rate. When you pay it as a seller, you are helping offset the cost of buying down the interest rate. There are two types of buydowns, one is a temporary buydown, the other is a permanent buydown.
A temporary buydown lowers the rate for the first couple of years, then it goes back to the full rate. This can work well for someone that is thinking about refinancing in a short time or maybe you know you have a raise coming that will help offset the payment. It could also be knowing a debt will go away – or maybe childcare costs will lower. You can get a temporary buydown for one to three years. The cost is the amount of interest you would have paid during that time.
A permanent buydown lowers the rate during the whole loan. These are paid with discount points. One point costs 1% of the loan amount, but it doesn’t lower the rate by 1%. Generally one point will lower the rate by about a quarter of a percent. This option works well for someone that plans to keep the home for a long time.
Here is an example of what a $10,000 concession could do. Here are three ways to spend the $10,000 and what it would save on a $420,000 30 year fixed rate loan at 7%.
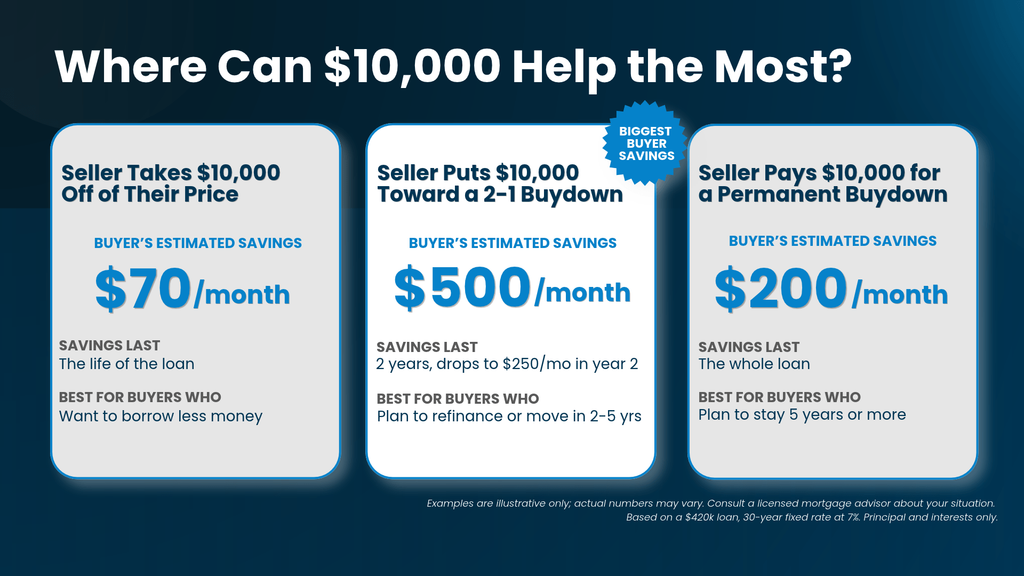
It’s the same $10,000 but it saves the buyer the most money on a temporary buydown. Because many buyers shop thinking about a monthly payment, that may help the most. However, buyers do need to remember it is temporary and that the payment will go up each year until they reach the full interest rate.
It does make it worth considering if you are thinking about lowering the price of your home. There are things to remember about this. There are some loans that will not allow temporary buydowns. There are also some caps to how much the seller can contribute to the buyer.
This is just one more way to make your home more appealing to buyers. Work with your realtor to figure out options to sell your home. Using a buydown may help you find a buyer for your home!
Leslie Vanderwerf, NMLS ID#335509, CrossCountry Mortgage LLC, An Equal Housing Lender, NMLS#3029 – Email – Website