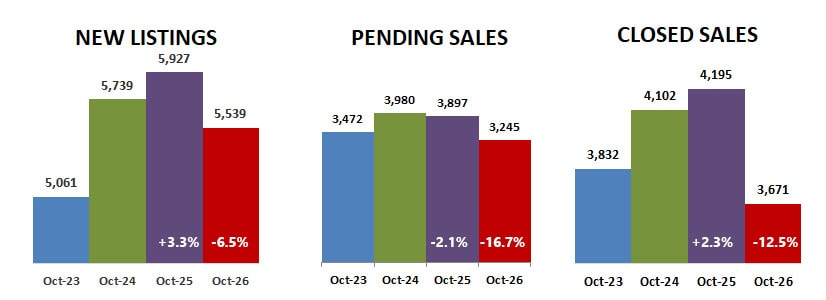
New listings, pending sales and closed sales all fell in October.
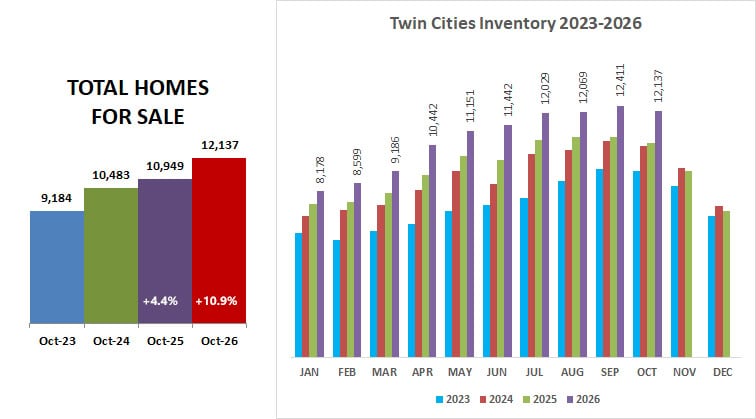
As sales dropped, total homes for sale rose 10.9% over last October.
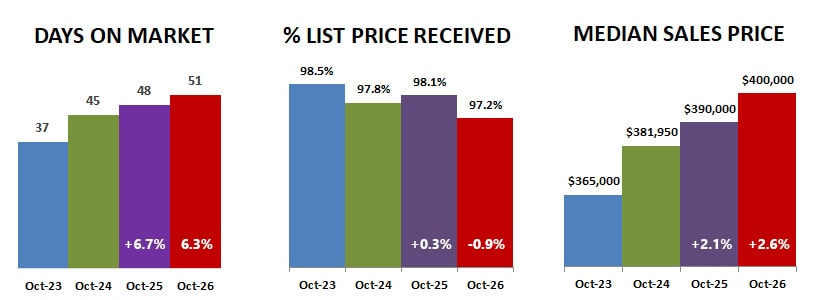
Percent of list price received fell, as days on the market until pending and median sales price continued to rise.
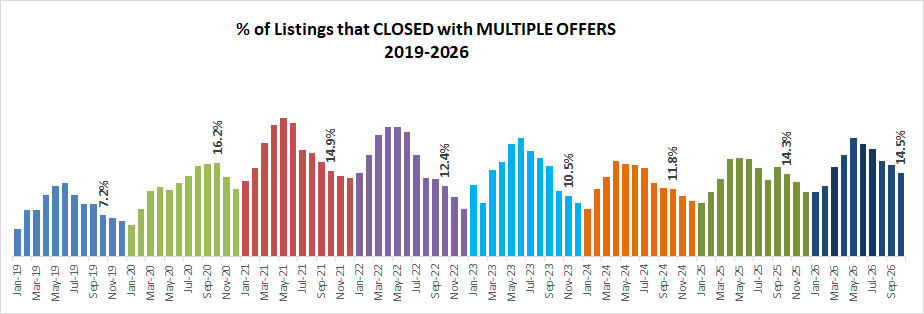
Multiple offers continued to be the strongest in the last 5 years, since during the pandemic in 2020 and 2021.
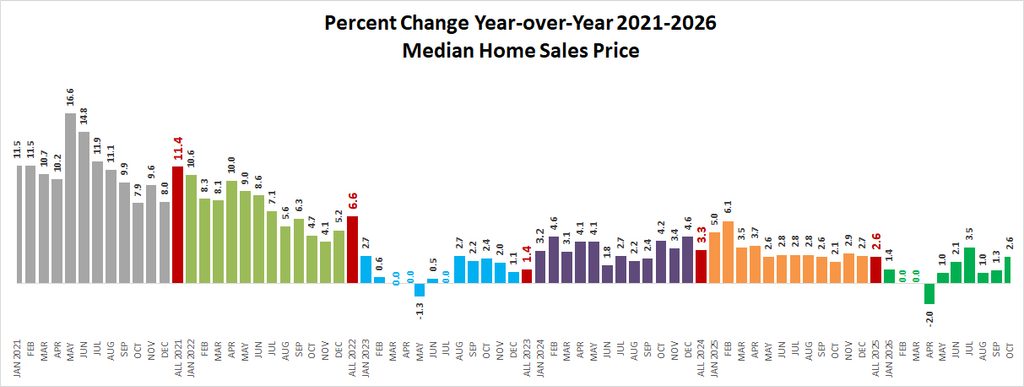
The multiple offers helped feed a slight increase in year-over-year percent change in median home sales prices.
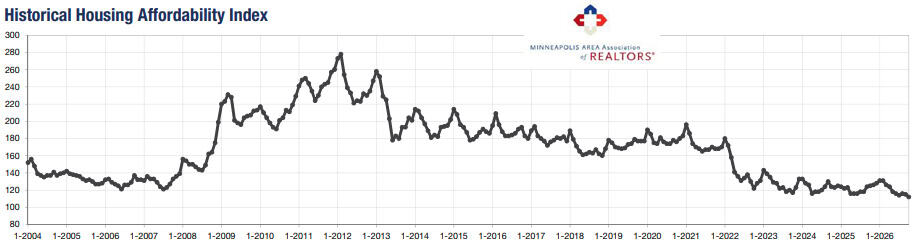
Amid all this, affordability tumbled to the lowest point on record going back to 2004.
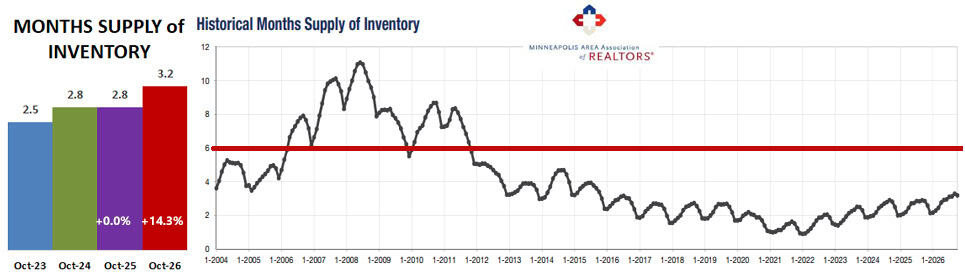
A bright spot for buyers, the months supply of inventory rose 14.3% over last October, to 3.2 months… still below the balanced market at a 6 month supply, but still an encouraging increase.
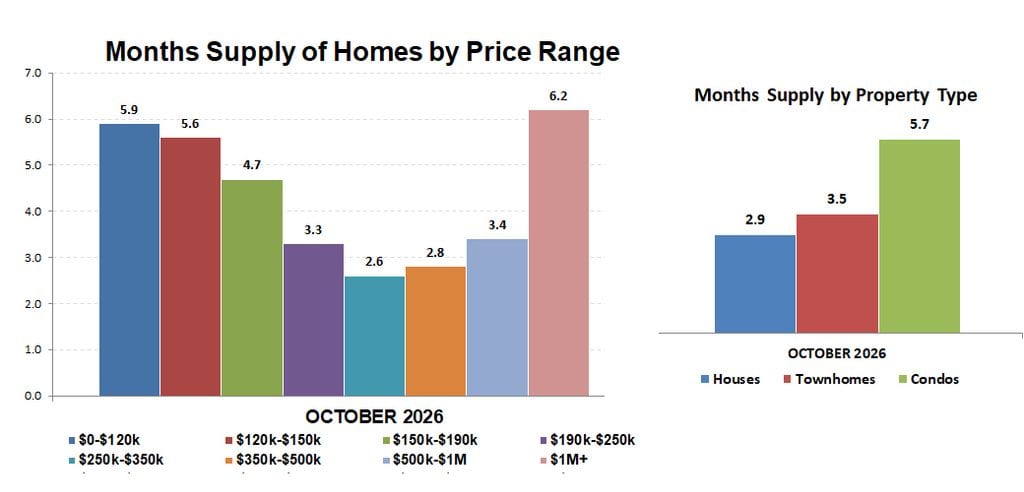
Looking at it by price range on the chart below, the $250k-$350k price range continues to be in highest demand, with a 2.6 month supply, but $350k-$500k isn’t far behind with a 2.8 month supply. Interesting that the lowest prices and highest prices are the ones reaching buyer’s market range of 5-6 months. Condos continue to have about double the months supply as houses… with more opportunities for buyers.
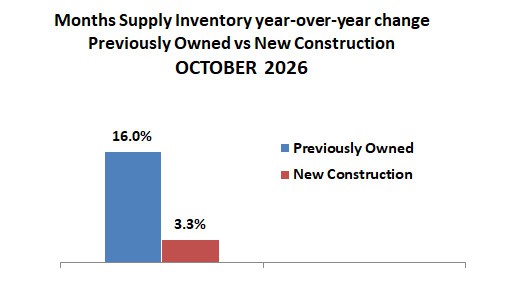
The change in supply of previously owned homes was the same as in September but new construction improved slightly, from a 1.6% increase to a 3.3% increase over last year.
The figures above are based on statistics for the combined 13-county Twin Cities metropolitan area released by the Minneapolis Area Association of Realtors.
Never forget that all real estate is local and what is happening in your neighborhood may be very different from the overall metro area.
Check with your Realtor for information on what is happening in your neighborhood.
Sharlene Hensrud, RE/MAX Results – shensrud@homesmsp.com
RELATED POSTS